Market overview of the Bariatric Products Market
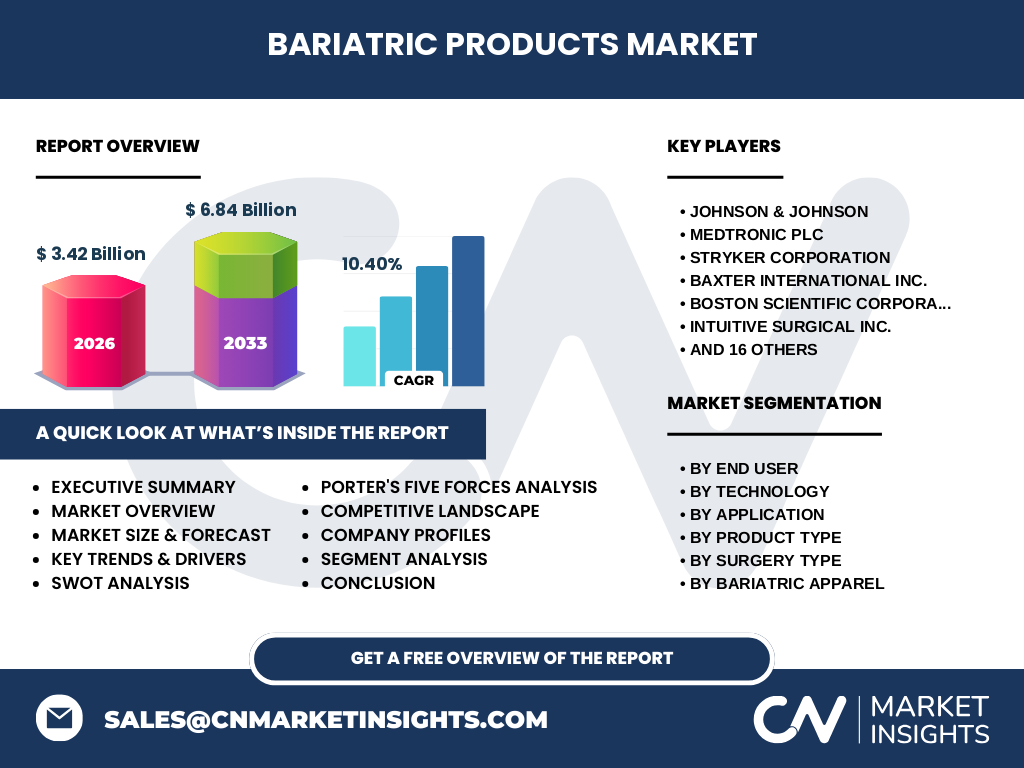
Our analysis indicates that the Bariatric Products Market size stands at 3.42 Billion in 2026. This specialized medical sector encompasses surgical instruments, advanced implants, mobility aids, and patient care devices designed to address severe obesity and associated comorbidities. Regulatory oversight by agencies such as the FDA ensures stringent compliance across all manufacturing nodes.
Key market drivers, restraints, challenges, and opportunities shaping Bariatric Products Market
The Bariatric Products Market industry trends are heavily propelled by rising obesity rates globally. However, stringent reimbursement policies and high upfront surgical costs act as notable restraints. Opportunities abound in emerging economies where healthcare infrastructure investments facilitate broader adoption of minimally invasive procedures.
Emerging trends and growth patterns in Bariatric Products Market
The Bariatric Products Market analysis reveals a distinct shift toward outpatient bariatric procedures. Minimally invasive technologies like robotic surgery systems are gaining traction over open surgeries. Patients increasingly prefer advanced non-invasive devices to mitigate postoperative recovery times and hospital stays.
COVID-19 impact analysis on Bariatric Products Market and recovery trajectory
The pandemic caused severe supply chain disruptions and delayed elective bariatric surgeries globally. Based on our research, the Bariatric Products Market experienced a V-shaped recovery starting in 2021, driven by surgical backlog clearances and accelerated adoption of telehealth pre-surgical screenings.
Competitive landscape and strategic dynamics in Bariatric Products Market
Market concentration in the Bariatric Products Market is moderately high, dominated by multinational medtech giants. Industry leaders leverage strategic mergers and acquisitions to expand their proprietary portfolios in surgical stapling, energy devices, and bariatric care infrastructure.
Executive summary of Bariatric Products Market research findings
Driven by robust clinical demand, the Bariatric Products Market size is projected to reach 6.84 Billion by 2033, expanding at a CAGR of 10.40% from 2027. Strategic investments in robotic platforms and implantable devices remain critical for capturing market share.
Market forecast for Bariatric Products Market from 2027 to 2033
Our long-term forecast demonstrates that the Bariatric Products Market will expand from 3.42 Billion in 2026 to 6.84 Billion by 2033. This expansion represents a steady 10.40% CAGR, fueled by rising metabolic disorder prevalence and technological innovations.
Segmentation analysis across product types and technologies
The Bariatric Products Market categorizes offerings by End User, Technology, Application, Product Type, and Surgery Type. Key segments include hospitals and ambulatory surgical centers utilizing laparoscopic devices, robotic surgery systems, and specialized bariatric beds to manage complex patient needs.
Regional market analysis and geographic distribution
Geographic performance in the Bariatric Products Market varies based on regional healthcare expenditures and obesity prevalence. North America maintains market dominance due to advanced reimbursement frameworks, while Asia-Pacific represents the fastest-growing regional segment.
In-depth regional review of key growth territories
North America leads the Bariatric Products Market due to high obesity rates and dense concentrations of specialized surgical centers. Meanwhile, European markets exhibit steady demand driven by strict regulatory approvals from bodies like the EMA for implantable gastric devices.
Company profiles and strategic positioning of leading firms
Industry giants like Johnson & Johnson, Medtronic plc, and Intuitive Surgical Inc. dominate through cutting-edge robotic systems and surgical instrumentation. Meanwhile, specialized players like Arjo AB and Drive DeVilbiss Healthcare capture significant share in patient care devices and mobility aids.
Porter's Five Forces analysis of the competitive environment
Our analysis indicates moderate-to-high competitive rivalry within the Bariatric Products Market, offset by high switching costs for proprietary robotic surgery systems. Supplier power remains moderate regarding raw medical-grade polymers, while buyer power is constrained by clinical efficacy requirements.
SWOT analysis of Bariatric Products Market ecosystem
Strengths include robust R&D pipelines and high clinical efficacy of bariatric implants. Weaknesses involve stringent regulatory approval hurdles. Opportunities lie in emerging home care settings, whereas threats stem from macroeconomic inflationary pressures affecting hospital capital expenditures.
Value chain analysis from raw materials to end-users
The value chain spans raw material sourcing of titanium and medical-grade silicone, precision manufacturing by firms like Teleflex Incorporated, and distribution through global logistics hubs to hospitals, clinics, and home care settings.
Investment insights and high-potential growth areas
Investors should target emerging non-invasive gastric balloons and ambulatory surgical center infrastructures. Companies focusing on robotic-assisted bariatric procedures offer superior risk-adjusted returns within the projected 2027 to 2033 forecast window.
Conclusion and key takeaways for stakeholders
The Bariatric Products Market represents a high-growth medical sector anchored by a 10.40% CAGR through 2033. Stakeholders must prioritize innovation in minimally invasive instruments and patient safety devices to maintain competitive advantage.
Research methodology for baseline estimations
Our analytical framework triangulates data from global trade registries, primary stakeholder interviews with bariatric surgeons, and secondary macroeconomic indicators to establish reliable baseline estimates for the Bariatric Products Market size.
Scope of the report and coverage parameters
This report covers the global Bariatric Products Market across major segments including surgery types, product categories, and regional markets from 2026 to 2033, excluding non-medical weight loss consumer goods and wellness supplements.
Recent developments, product launches, and strategic partnerships
Recent industry momentum features FDA clearances for novel intragastric balloons by innovators like Spatz FGIA Inc. and strategic distribution partnerships established by Boston Scientific Corporation to expand their bariatric surgical instrument reach globally.